Author name: Joe L.

Wide horizontal editorial photo, warm natural morning light streaming through a large kitchen window. A man and woman bo
Retirement

Should a 55-Year-Old in the 22 Percent Tax Bracket Open a Roth IRA or Traditional IRA?

At 55, the Roth IRA versus Traditional IRA decision has consequences that stretch 30 years into the future. Most people in the 22 percent tax bracket choose wrong because they focus on the current-year deduction and ignore required minimum distributions, IRMAA Medicare surcharges, and the tax flexibility a Roth balance gives you in retirement. Here is the honest math on which account wins at 55.
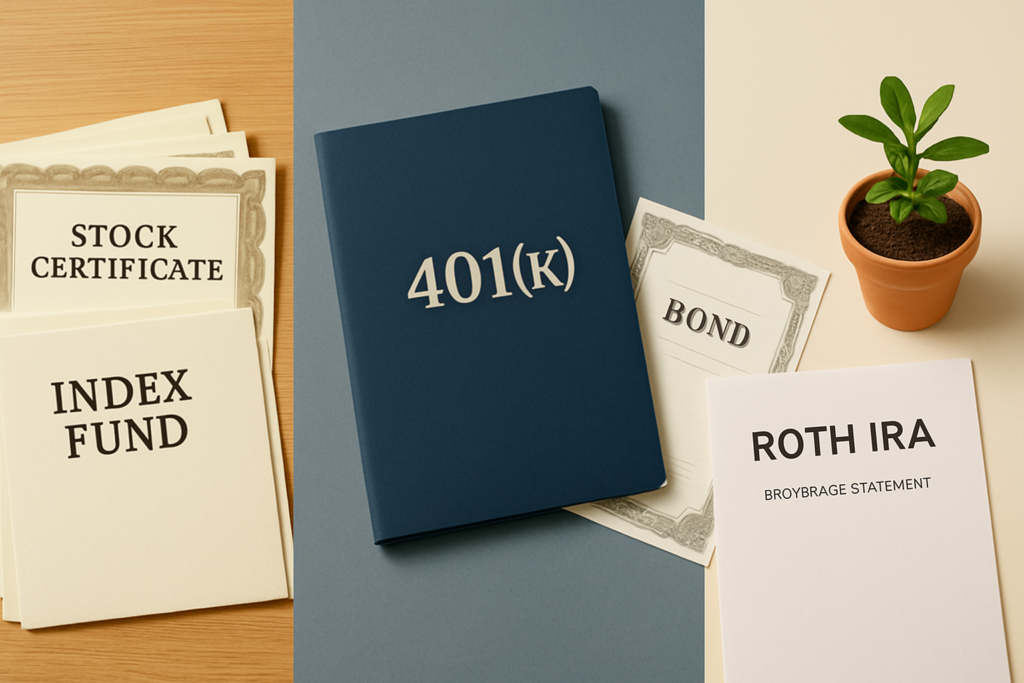
Wide horizontal editorial abstract conceptual photo of tax-efficient asset location for an investing article — a clean,
Investing

Which Investments Should Go in Your Roth IRA, 401k, and Taxable Account?

Most investors spend time picking the right funds — but where you hold them matters just as much as what you hold. Put bonds in a taxable account, REITs in a brokerage, and growth funds in the wrong place, and you could pay tens of thousands in unnecessary taxes over 20 years. Joe L. breaks down the three-account framework: taxable brokerage for tax-efficient index funds, 401k/Traditional IRA for bonds and high-income assets, and Roth IRA for your highest-growth holdings.

wide horizontal editorial photo, ABSTRACT/CONCEPTUAL style, a clean split composition across the full width of a warm ne
Investing

Are Qualified Dividends Taxed at 15% or 22%? What the Rules Actually Mean for a Middle-Income Investor

Most 22% bracket investors assume their dividends are taxed at 22%. They're not. Qualified dividends — dividends from most U.S. stocks and broad index funds held long enough — are taxed at 15% for middle-income investors, not at your ordinary income rate. That changes where you should hold dividend investments, how to read your 1099-DIV, why REITs and bond fund distributions belong in a different account, and what the real annual tax drag looks like on a $50,000 taxable position.

wide horizontal editorial photo, ABSTRACT/CONCEPTUAL style, a clean minimalist investment-themed flat-lay arrangement sp
Investing

Vanguard vs Fidelity vs Schwab: Which Brokerage Is Best for a 45-Year-Old With $120,000 to Invest?

All three brokerages charge $0 commissions on stock and ETF trades, and all three are safe, regulated, and reliable. So what actually separates Vanguard, Fidelity, and Schwab for a 45-year-old building a real long-term portfolio? This breaks down the differences that matter — expense ratios on index funds, fractional share investing, platform usability, customer service, and IRA rollover experience — and gives a direct verdict on which platform fits most mid-career investors best.

wide horizontal editorial photo, DISTANT OR SILHOUETTED PEOPLE style, a man and woman in their early 60s shown from behi
Retirement

The SECURE 2.0 Super Catch-Up: How Much More Can You Put in Your 401k at Ages 60 to 63?

Most people know about the standard 401(k) catch-up contribution after age 50. Fewer people know that SECURE 2.0 created a higher "super catch-up" limit exclusively for ages 60, 61, 62, and 63 — and that it drops back down at 64. This explains what the super catch-up actually allows, what it means in real dollar terms over a four-year window, whether your plan has adopted it, and how to use this last pre-retirement sprint to close the gap before you stop contributing entirely.

wide horizontal editorial photo, DISTANT OR SILHOUETTED PEOPLE style, a late-afternoon scene spread across the full widt
Retirement

What Is the Step-Up in Basis Rule and How Much Tax Does It Save on Inherited Stock?

The step-up in basis rule is one of the most valuable tax provisions most Americans have never heard of. When you inherit stocks, mutual funds, or a taxable brokerage account, the IRS automatically resets your cost basis to the fair market value on the date of death — wiping out all the capital gains that accumulated during the original owner’s lifetime. On $125,000 in inherited stock with an $81,000 embedded gain, that’s $12,000–$16,000 in federal taxes that simply disappear. Here’s the real dollar math, what qualifies and what doesn’t, and how to use this rule in your own estate planning.

wide horizontal editorial photo, DISTANT OR SILHOUETTED PEOPLE style, a person in their late thirties viewed from slight
Retirement

Solo 401k vs SEP-IRA: Which Is Better for a Self-Employed Person, and How Much Can You Actually Contribute?

A self-employed person with $80,000 in net income can contribute roughly $38,000 to a Solo 401k but only about $16,000 to a SEP-IRA — on the same income. Most people pick the SEP because it’s simpler without realizing they’re leaving more than $20,000 in annual tax-deferred contribution room on the table. Here’s the complete comparison: contribution limits at different income levels, the Roth advantage the SEP-IRA doesn’t have, the backdoor Roth complication that makes the SEP a trap for some investors, and a clear decision framework for choosing the right account.

wide horizontal editorial photo, ABSTRACT/CONCEPTUAL style, a clean wide-format graphic composition showing two distinct
Retirement

Should a 62-Year-Old Retiree Invest for Dividends or Total Return? An Honest Answer

The debate between dividend investing and total return is one of the most emotionally charged in retirement planning — and it has a real answer. Total return wins on the math. Dividends win on the psychology. Here’s what actually matters for a 62-year-old deciding how to structure their portfolio, including the sector concentration trap most dividend investors walk into, the tax math during the pre-Social Security window, and the cash buffer strategy that solves the behavioral problem better than any yield-chasing approach.

wide horizontal editorial photo, OBJECTS/FLAT-LAY style, a carefully arranged row of financial documents spread across t
Retirement

How Much of My Portfolio Should Be in Bonds at 55, 60, and 65? An Honest Answer

The old rule of subtracting your age from 110 to find your stock allocation was built for a generation that retired at 65 and died at 72. Today’s 60-year-old needs a portfolio to last 25-30 years — and being 50% in bonds at 60 is a quiet way to underfund that runway. Here are the allocation targets that actually make sense at 55, 60, and 65, plus the income-source variable that changes everything.

Scroll to Top